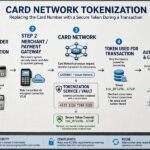
Payment tokenization has two major models, distinguished by who issues and manages the tokens: the card network (Visa, Mastercard) or the issuer (your bank). They sound similar — both replace card numbers with surrogates — but the architectural differences affect interoperability, control, and which transactions they cover. Understanding the distinction matters if you’re building payment systems or just want to know what’s protecting your taps.
This guide compares the two models directly. For the general technology, see how tokenization works.
Table of Contents
- The Short Version
- Network Tokenization: The Network Issues Tokens
- Issuer Tokenization: The Bank Issues Tokens
- Side-by-Side Comparison
- Interoperability: The Key Difference
- Control and Customization
- Security Model Comparison
- When Each Makes Sense
- Migrating Between the Models
- The Converging Future
- Frequently Asked Questions
The Short Version
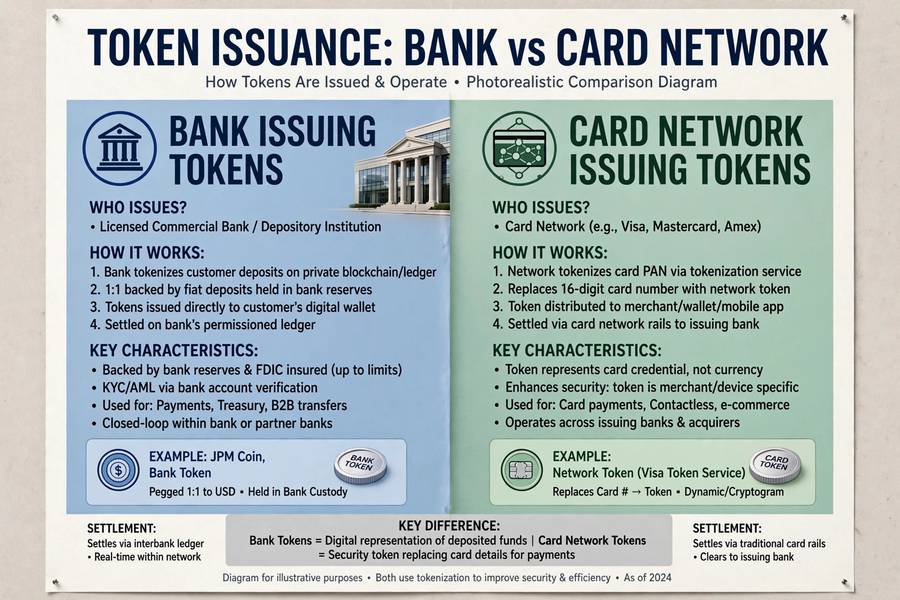
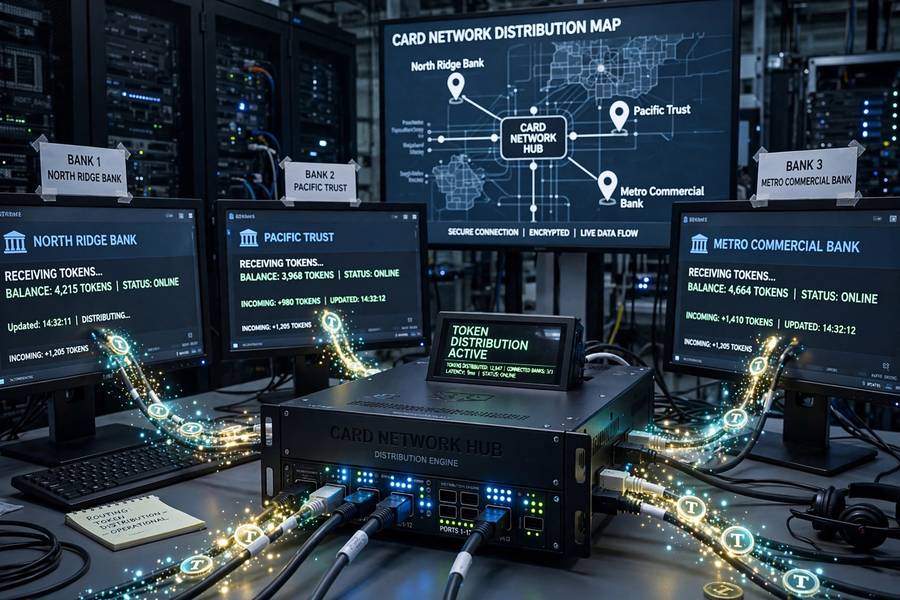
Network tokenization: the card network (Visa, Mastercard) issues and manages tokens. Tokens work across the network’s entire ecosystem — any merchant, any acquirer on that network. The network operates the vault.
Issuer tokenization: the issuing bank (or its processor) issues and manages tokens. Tokens work within the issuer’s domain — its cards, its systems, its partnerships. The issuer operates the vault.
The core difference: scope of acceptance. Network tokens are universally accepted on the network; issuer tokens are accepted where the issuer has arranged acceptance. Everything else — security properties, lifecycle management, the surrogate principle — is similar.
Network Tokenization: The Network Issues Tokens
The dominant model for consumer payments:
Who: Visa, Mastercard, and other card networks operate tokenization platforms (Visa Token Service, Mastercard Digital Enablement Service).
Scope: any merchant and acquirer on the network, globally. A Visa token works at any Visa-accepting merchant worldwide — the network’s ubiquity is the point, and it’s why network tokens have become the default credential for what e-commerce is at scale.
The vault: operated by the network. The network maps tokens to PANs during transaction processing.
Provisioning: through wallets (Apple Pay, Google Pay), merchants, and issuers — all requesting from the network’s platform.
Standards: EMVCo tokenization specifications — the industry standard ensuring interoperability. Network tokenization follows these specs, which is why a token provisioned for one wallet works across the ecosystem.
The strength: universality. One tokenization system, global acceptance, standardized behavior. The network effects are enormous — merchants integrate once, tokens work everywhere.
Issuer Tokenization: The Bank Issues Tokens
The alternative model, where issuers take control:
Who: issuing banks (or their processors) operate their own tokenization — generating tokens, maintaining vaults, managing lifecycles.
Scope: the issuer’s domain — its issued cards, its partner merchants, its digital channels. Acceptance depends on the issuer’s integrations, not automatic network-wide acceptance.
The vault: operated by the issuer (or its designated processor). The issuer maps tokens to accounts.
Use cases: issuer-specific digital products, proprietary wallets, closed-loop scenarios, and situations where the issuer wants control beyond what network tokenization offers.
The motivation: control and differentiation. Issuers may want tokenization behaviors the network doesn’t offer — custom token policies, integration with their own fraud systems, proprietary experiences, or coverage for transaction types outside the network’s scope.
Side-by-Side Comparison
| Dimension | Network Tokenization | Issuer Tokenization |
|---|---|---|
| Token issuer | Card network | Issuing bank/processor |
| Acceptance scope | Network-wide (global) | Issuer’s domain/integrations |
| Vault operator | Network | Issuer/processor |
| Standards | EMVCo specifications | Varies (may follow EMVCo) |
| Interoperability | High (standardized) | Limited to integrations |
| Issuer control | Standardized behaviors | Custom policies possible |
| Implementation | Via network platforms | Build or buy issuer solution |
| Best for | General consumer payments | Proprietary/closed-loop needs |
Neither is universally superior — they serve different scopes with different trade-offs.
Interoperability: The Key Difference
This is where the models diverge most consequentially:
Network tokens interoperate by design. EMVCo standards mean a network token works across merchants, acquirers, wallets, and geographies on that network. The ecosystem coordinates around the standard — that’s the network’s fundamental value proposition.
Issuer tokens interoperate by arrangement. Each acceptance point requires integration — the merchant’s acquirer must route to the issuer’s token system, the wallet must support it. This works within partnerships but doesn’t scale to “everywhere” automatically.
The practical consequence: for general-purpose consumer payments (buy anything, anywhere), network tokenization’s interoperability is decisive. For contained ecosystems (a bank’s own app, a closed-loop program, specific partnerships), issuer tokenization’s control may outweigh interoperability needs.
The analogy: network tokenization is like the postal system — standardized, universal. Issuer tokenization is like a courier service — customized, bounded. Both deliver; the choice depends on the route.
Control and Customization
Where issuer tokenization justifies itself:
Custom token policies. Issuers can define token behaviors beyond network standards — special expiration rules, custom domain restrictions, integration with proprietary risk systems.
Data and analytics. Issuer-operated tokenization keeps transaction intelligence within the issuer’s systems — valuable for fraud modeling and customer insights.
Product differentiation. Proprietary token experiences — unique wallet features, integrated loyalty, custom flows — that standardized network tokenization doesn’t support.
Non-network transactions. Account-to-account transfers, closed-loop programs, and other flows outside card network rails — where network tokenization doesn’t apply by definition.
The trade-off: control costs interoperability and scale. Issuers choosing their own tokenization accept integration burden in exchange for differentiation. It’s the classic build-vs-buy tension applied to payment security infrastructure.
Security Model Comparison
Both models share the core security properties — surrogate tokens, vault mappings, domain binding, lifecycle management. The differences are in trust boundaries:
Network model trust: concentrated in the network’s vault and infrastructure. The network is the trusted third party — already trusted for settlement, now also for token mapping.
Issuer model trust: concentrated in the issuer’s systems. Fewer parties involved (no network vault in the path), but the issuer bears the full security burden.
Attack surface: network tokenization’s vault is a bigger target (more tokens, more issuers’ data) but defended with network-scale resources. Issuer vaults are smaller targets with (typically) fewer defensive resources.
The assessment: both are sound when implemented well. The network model’s scale advantages in defense are real; the issuer model’s reduced third-party exposure appeals to control-focused organizations. Security quality depends more on implementation rigor than on model choice.
When Each Makes Sense
Choose network tokenization when: – General consumer payments across many merchants – Interoperability matters (acceptance everywhere) – You want standardized, proven infrastructure – Time-to-market matters (platforms exist, integrate and go)
Choose issuer tokenization when: – Proprietary payment experiences or closed-loop programs – Transactions outside network rails – Custom token behaviors beyond network standards – Strategic control over the token layer justifies the investment – Regulatory or business requirements demand issuer custody
Use both when: – Different transaction types need different models (network for open-loop, issuer for proprietary) – Defense in depth across layers – Migrating between models over time
Most of the payment world runs on network tokenization for consumer transactions, with issuer tokenization serving specialized needs. The coexistence is stable — they address different scopes, not competing for the same one.
Migrating Between the Models
Organizations sometimes need to move — typically from issuer-operated tokenization toward network tokenization as their transaction footprint outgrows the issuer’s domain. The migration is a serious undertaking, and the failure modes are specific.
Why migrations happen. The usual trigger is scale: an issuer tokenization system built for a proprietary wallet now needs to support third-party wallets, new geographies, or merchant categories the issuer’s integrations don’t cover. The interoperability ceiling arrives, and network tokenization’s universality becomes the answer. Less commonly, the reverse — an organization pulls tokenization in-house for strategic control after outgrowing what the network’s standardized offering provides.
The core challenge: token inventory. The migration isn’t just switching a configuration — it’s re-provisioning. Every active issuer token must be replaced with a network token, which means touching every stored credential, every wallet enrollment, every merchant token store. For a large issuer, that’s millions of tokens with individual lifecycles, and each re-provisioning requires cardholder verification steps that can’t be skipped without weakening the security model.
The sequencing. Successful migrations run in phases, not flag-days: first, dual-provisioning — new enrollments get network tokens while existing issuer tokens continue working. Then, gradual re-provisioning of the installed base, prioritized by activity (active wallets first, dormant credentials later). Then, a sunset window for the remaining issuer tokens with clear communication. Throughout, both token systems must process transactions — the routing layer has to know which token type each credential is and direct it correctly.
What goes wrong. The classic failure is underestimating the long tail — the 5% of tokens belonging to inactive users, legacy integrations, or forgotten merchant connections that nobody owns anymore. These surface at the worst moment: the sunset deadline, when killing the old system breaks a payment flow nobody remembered existed. The mitigation is an honest inventory before committing to a timeline, plus a sunset window measured in quarters, not weeks.
The strategic lesson. Tokenization model choice has migration costs that should factor into the original decision. Choosing issuer tokenization for control is legitimate — but price in the eventual migration if (when) scale demands network interoperability. The cheapest migration is the one you planned for on day one.
The Converging Future
The models are converging in interesting ways:
Standards spreading. EMVCo specifications increasingly cover issuer implementations — the interoperability gap narrows as standards adopt.
Hybrid architectures. Issuers using network tokenization for standard flows and proprietary tokenization for differentiated experiences — pragmatic coexistence.
Tokenization as infrastructure. Both models maturing into reliable utilities — the innovation moving to what tokens enable (programmable credentials, embedded finance) rather than who issues them.
The long view: the distinction may matter less over time as standards harmonize and the token layer becomes invisible infrastructure. What persists is the architectural principle — surrogate credentials, centralized mapping, distributed use — regardless of who operates the vault.
Frequently Asked Questions
Network tokenization: the card network issues tokens accepted network-wide (global interoperability, EMVCo standards). Issuer tokenization: the bank issues tokens for its own domain (more control and customization, limited to its integrations). Same surrogate principle; different scope and operator.
Neither universally — network tokenization wins on interoperability for general consumer payments; issuer tokenization wins on control for proprietary or closed-loop scenarios. Most of the payment world uses network tokenization for open transactions, issuer tokenization for specialized needs.
No — issuer tokens work within the issuer’s integrations and partnerships, unlike network tokens which work at any merchant on the network. Interoperability is the key difference: network tokens interoperate by standard; issuer tokens interoperate by arrangement.
For control and differentiation: custom token policies, integration with proprietary fraud systems, unique product experiences, coverage of non-network transaction types, and keeping transaction intelligence in-house. The trade-off is accepting integration burden for that control.
Yes — EMVCo standards increasingly cover issuer implementations, hybrid architectures are common (network for standard flows, issuer for proprietary), and the innovation focus is shifting to what tokens enable rather than who issues them. The architectural principle persists regardless of operator.