I’ve sat on both sides of the table — advising small companies and reviewing plans for lenders. Here’s what I learned: most business plans fail before page three, not because the idea is bad, but because the writer confused a business plan with a sales pitch.
A business plan that convinces someone your idea is amazing. It’s a document that proves you’ve thought about how the money works. I don’t do motivational fluff. Let’s break down the real decisions, the real numbers, and the real mistakes.
Table of Contents
- What a Business Plan Actually Is (and Isn’t)
- Who Needs One and Who Doesn’t
- The 7 Sections That Matter
- The Executive Summary: Write It Last
- Market Analysis Without the Fantasy
- The Financials: Where Most Plans Die
- The Mistakes That Kill Business Plans
- The One-Page Version
- How Long This Actually Takes
- Frequently Asked Questions
What a Business Plan Actually Is (and Isn’t)
A business plan is an operating document. It answers five questions:
- What do you sell, and to whom?
- Why will they buy from you instead of someone else?
- How does the money flow — costs in, revenue out?
- What can go wrong, and what’s your response?
- What do you need (money, people, time) to make it work?
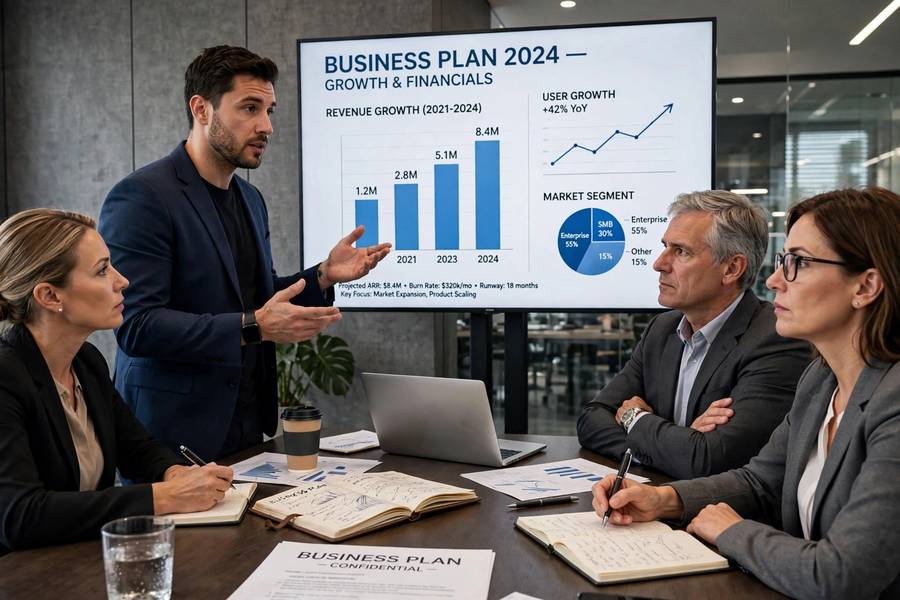
That’s it. It’s not a vision statement. It’s not a 40-page market research report. It’s a decision-making tool — first for you, second for anyone whose money or time you’re asking for.
The plans that get funded share one trait: the numbers are honest. I’d rather see realistic thin margins than fantasy hockey-stick growth. Anyone who’s run a business can smell invented numbers in about ninety seconds.
Who Needs One and Who Doesn’t
You need a written plan if:
- You’re borrowing money. Banks require one. No plan, no loan — it’s that simple.
- You’re raising investment. Investors want to see that you’ve modeled the downside, not just the upside.
- You’re bringing on partners. A plan forces the hard conversations (equity splits, roles, exit terms) before money is involved.
- The business is complex. Multiple revenue streams, inventory, staff — write it down or lose track of it.
You probably don’t need a formal 20-page plan if you’re freelancing, running a side hustle, or testing an idea. A one-page version (see below) is plenty until real money is at stake. Don’t let “writing the plan” become procrastination disguised as preparation. I’ve watched founders spend four months perfecting a document for a business they never started.
If you’re still deciding whether the entrepreneurial path fits you at all, read up on how to become an entrepreneur first — the plan comes after the decision.
The 7 Sections That Matter
Forget the 12-section templates. These seven cover everything a reader needs:
1. Executive summary
One page. What the business does, who it serves, what you need, and why it’ll work. Written last, read first.
2. Company description
Legal structure, location, what you sell, and your unfair advantage. Two paragraphs is fine. If you can’t explain the business in two paragraphs, you don’t understand it yet.
3. Market analysis
Who buys, how many of them exist, who else serves them, and where the gap is. Real data, cited sources, no “the global market is $4 trillion so we’ll capture 1%.”
4. Organization and management
Who runs what. Bios with relevant experience, not resumes. Gaps acknowledged honestly (“we’ll hire a bookkeeper in month six”) score more points than pretending you do everything.
5. Products and services
What you sell, what it costs you, what you charge, and your margins. This is where what branding really means connects — your positioning determines your pricing power.
6. Marketing and sales
How customers find you, what it costs to acquire one, and how you’ll keep them. Vague “social media marketing” plans get rejected. Specific channels with estimated costs get taken seriously.
7. Financial projections
Three years of projected income statements, cash flow, and a break-even analysis. This section carries more weight than the other six combined.
The Executive Summary: Write It Last
Everyone wants to write this first. Don’t. You can’t summarize a plan you haven’t written.
When you do write it, remember who reads it: a busy person deciding whether to read further. Lead with the essentials — business concept in two sentences, target market, what you’re asking for (loan amount, investment), and the one number that matters most (projected year-one revenue, break-even point, or similar).
Keep it to one page. If your summary needs two pages, your thinking isn’t finished.
Market Analysis Without the Fantasy
This is where most plans go off the rails. Founders love quoting enormous total addressable markets. “The pet industry is $150 billion!” Great. How many dog owners within 20 miles of your store will actually walk in? That’s your market.
Do this instead:
- Size your reachable market. Geography, demographics, realistic penetration. Small honest numbers beat big fantasy numbers.
- Name your competitors. All of them, including the “we have no competitors” delusion. If you truly have no competitors, you probably have no market.
- Explain your edge specifically. Not “better customer service” — everyone claims that. What’s structurally different? Lower costs? Exclusive supply? A location advantage? A skill nobody local has?
I once reviewed a plan for a coffee shop that listed twelve competitors within a mile and then explained, with foot-traffic counts, why the corner location captured morning commuters the others missed. That’s market analysis. “People love coffee” is not.
The Financials: Where Most Plans Die
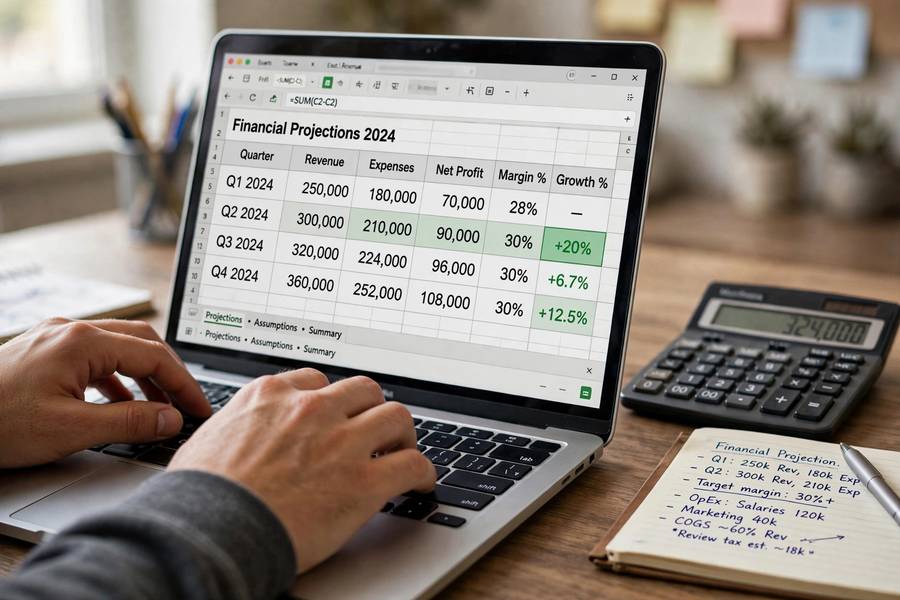
I’ll be direct: this section decides everything. A lender flips to the financials first. Here’s what to include and what they’re actually checking:
Startup costs. Every dollar you need before revenue starts — equipment, deposits, licenses, initial inventory, and three to six months of operating expenses. Founders chronically underestimate this by 30–50%. Add a 20% contingency line and you’ll look like someone who’s done this before.
Three-year projections. Monthly for year one, quarterly for years two and three. Income statement (revenue, costs, profit), cash flow statement (when money actually moves — this is the one that kills businesses), and balance sheet.
Break-even analysis. Exactly how many units or customers per month cover your costs. If you don’t know this number cold, you’re not ready.
Assumptions page. List every assumption behind your numbers — pricing, customer acquisition cost, conversion rates, growth rates. Honest assumptions with sources beat optimistic guesses every time.
The mistake I see most: revenue projections based on hope, cost projections based on optimism. Flip it. Be conservative on revenue, generous on costs. If the plan still works, you have a real business. If it only works with perfect conditions, you have a hobby with a spreadsheet.
And understand what kind of entity you’re building — the financial expectations for what a startup actually is differ wildly from a traditional small business, and your plan should reflect that.
The Mistakes That Kill Business Plans
After reviewing hundreds of plans, the fatal errors repeat:
- No cash flow projection. Profit on paper means nothing if you’re out of cash in month four. Businesses die from cash flow, not from lack of profit.
- Ignoring the downside. No risk section, no “what if we’re 50% below projection.” Readers assume you’re naive or dishonest. Include the bad scenarios and your responses.
- Founder salary fantasy. Either the founder takes no salary (unsustainable — you’ll quit) or an inflated one (kills the numbers). Pay yourself a realistic modest salary from month one.
- Copy-paste templates. Readers can tell. A generic plan signals a generic business.
- Hiding the competition. Claiming no competitors destroys credibility instantly.
- Unrealistic timelines. “Profitable in month two” for a retail business is fiction. Research real ramp-up times for your industry.
The One-Page Version
For internal use, partnerships, or early conversations, use this format. Nine boxes, one page:
- Problem — what pain do customers have?
- Solution — what do you sell?
- Customers — who exactly buys?
- Value proposition — why you, specifically?
- Channels — how do they find you?
- Revenue — how does money come in?
- Costs — where does money go out?
- Key metrics — the 2–3 numbers you’ll watch weekly.
- Unfair advantage — what can’t be easily copied?
If you can’t fill this in an afternoon, the idea needs more thought — which is exactly what the exercise is for.
How Long This Actually Takes
A solid plan takes two to four weeks of real work — not full-time, but consistent effort. Most of that time goes to research and financial modeling, not writing. The writing itself is a few days once the thinking is done.
Don’t hire someone to write it for you. A consultant-written plan you don’t understand is worse than no plan — you’ll be defending numbers you can’t explain in front of people whose money you want. Get help with the financial modeling if you need it, but the thinking has to be yours.
Frequently Asked Questions
Start with research: your market, competitors, and costs. Then write the seven core sections — company description, market analysis, organization, products, marketing, and financial projections — and finish with the one-page executive summary. Build conservative financials first; the narrative follows the numbers, not the other way around.
The seven essential parts are: executive summary, company description, market analysis, organization and management, products and services, marketing and sales strategy, and financial projections. The financial projections — including startup costs, three-year forecasts, cash flow, and break-even analysis — carry the most weight with lenders and investors.
15–25 pages is the sweet spot for a formal plan going to a bank or investors. Anything longer usually means unfocused thinking. For internal use or early-stage ideas, a one-page plan covering the problem, solution, customers, revenue, costs, and key metrics is enough.
Include startup costs with a contingency buffer, three-year projected income statements (monthly for year one), cash flow projections, and a break-even analysis. Add an assumptions page listing every number behind your projections. Lenders scrutinize cash flow most — businesses fail from running out of cash, not from lack of paper profit.
Yes — banks require one for most small business loans. They focus on your financial projections, break-even analysis, collateral, and your ability to repay. A realistic plan with honest numbers and acknowledged risks gets approved far more often than an optimistic one with fantasy growth curves.
Skipping the cash flow projection. Founders model profit but forget that profit on paper doesn’t pay next month’s rent — timing of cash in versus cash out is what kills businesses. The second biggest mistake is ignoring downside scenarios; plans that only show the rosy case lose credibility immediately.