Discounted Cash Flow Valuation Simplified: A Plain-English Guide
Discounted cash flow (DCF) has a reputation as the most intimidating valuation method — all those projections, discount rates, and terminal values. Investment bankers wield it like a priesthood ritual. But the underlying idea is simple: a business is worth the cash it’ll generate in the future, adjusted for the fact that future cash is worth less than cash today.
I’ve built DCF models for acquisitions and simplified them for owners who’ve never opened a spreadsheet. Here’s the method stripped to its essentials — what matters, what’s noise, and how to use it without a finance degree.
The Core Idea in One Paragraph
A dollar today is worth more than a dollar in five years — because you could invest today’s dollar, and because the future is uncertain. DCF applies this logic systematically: project the business’s cash flows for 5 years, discount each year’s cash back to today’s value (higher discount = more risk), add a ‘terminal value’ for all years beyond the projection, and sum it up. That sum is the business’s intrinsic value.
That’s it. Everything else is detail. The method is theoretically the purest valuation approach — it values the actual thing being purchased (future cash) rather than proxies (multiples of past earnings). Its weakness is also its purity: the result is only as good as the projections, and projections are guesses.
When to use DCF: as a cross-check on multiple-based valuations, for high-growth businesses where history understates potential, and when you need to test whether a multiple-based price makes economic sense. When NOT to use it: as your sole valuation method for a small business sale — buyers won’t pay based on your spreadsheet fantasies. selling a business
Step 1: Project Free Cash Flow (5 Years)
Free cash flow = operating cash flow minus capital expenditures — the cash the business generates after maintaining itself. Project it for 5 years based on: historical growth rates (the anchor — don’t project 30% growth for a business that’s grown 5%), known changes (signed contracts, planned expansions, cost changes), and industry outlook (tailwinds or headwinds).
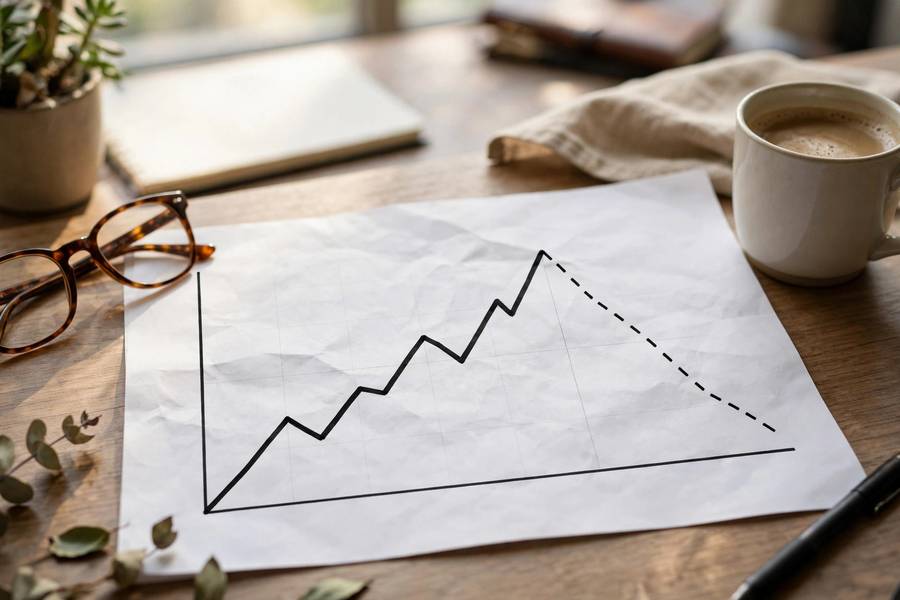
Be honest about the trajectory: most small businesses should be projected with modest growth (3–8% annually) unless there’s specific, defensible reason for more. The classic DCF abuse is projecting hockey-stick growth — flat for 2 years, then 40% jumps. If the growth isn’t contracted or historically demonstrated, it’s fiction.
Year-by-year detail matters less than the overall shape. A simple approach: start with current normalized free cash flow, apply a defensible growth rate, and adjust for known one-time items. Precision in year 4 of a 5-year projection is false precision — the discounting makes distant years matter less anyway. For the valuation framework, my business valuation guide shows where DCF fits.
Step 2: Choose a Discount Rate
The discount rate reflects risk — higher risk, higher rate, lower present value. For small businesses, 15–25% is typical (versus 8–12% for large public companies). The components: risk-free rate (~4–5% — what government bonds pay), plus equity risk premium (~5–6%), plus small-company premium (~4–6%), plus company-specific risk (0–10% for concentration, owner dependence, industry risk).
In practice: a stable, diversified small business might warrant 15–18%; a riskier one (customer concentration, owner-dependent, cyclical) 20–25%. Don’t overthink the precision — the difference between 18% and 20% matters less than getting the cash flow projections honest.
The sensitivity reality: DCF results swing wildly with the discount rate. A business generating $200K growing at 5% is worth ~$1.1M at 20% discount, ~$1.5M at 15%. That’s a 36% swing from a 5-point rate change. This sensitivity is DCF’s dirty secret — it means the method is better for testing reasonableness than for pinpointing value. Always run multiple rates.
Step 3: Calculate Terminal Value
Beyond year 5, you can’t project meaningfully — so you assume the business reaches steady state and grows at a perpetual rate (typically 2–3%, roughly long-term economic growth). Terminal value = Year 5 cash flow × (1 + perpetual growth rate) ÷ (discount rate − perpetual growth rate).
Example: Year 5 cash flow $250K, perpetual growth 2.5%, discount rate 18%. Terminal value = $250K × 1.025 ÷ (0.18 − 0.025) = $256,250 ÷ 0.155 = $1.65M. Then discount THAT back 5 years to present value: $1.65M ÷ (1.18^5) = $722K.
The uncomfortable truth: terminal value often represents 60–80% of total DCF value. You’re valuing ‘forever’ based on a formula — which means small changes in perpetual growth or discount rate create enormous swings. Keep perpetual growth at or below 3% (above long-term GDP growth forever is fantasy), and recognize that most of your ‘valuation’ is this single assumption. Humility is warranted.
Step 4: Sum and Sanity-Check
Add the present values: discounted years 1–5 cash flows + discounted terminal value = enterprise value. Then adjust for cash, debt, and working capital (same as other methods) to reach equity value.
Now the critical step most people skip: sanity-check against multiples. If your DCF says $2M for a business with $300K EBITDA, that’s 6.7x — is that reasonable for the industry? If comps trade at 4x, your DCF is probably optimistic (check the growth assumptions and discount rate). The DCF doesn’t override market reality; it must reconcile with it.
Also reverse-engineer: what growth and discount assumptions would justify the seller’s asking price? If the ask requires 25% perpetual growth at a 12% discount rate to make sense, the ask is fantasy — and you now have the math to prove it. DCF is most powerful as a bullshit detector, not as a pricing tool.
DCF vs. Multiples: Which to Trust
Multiples reflect what the market actually pays — they’re empirical. DCF reflects what the business is theoretically worth — it’s analytical. When they agree, confidence is high. When they disagree, investigate: the market might be wrong (opportunity), or your DCF might be wrong (more likely — check assumptions).
In practice: use multiples for pricing (they’re what buyers pay), use DCF for validation (it tests whether the multiple makes economic sense). If a 4x multiple implies cash flows that a reasonable DCF can’t support, either the multiple is wrong or the business has value the DCF misses (strategic value, synergies, asset appreciation).
For small business sales specifically: lead with multiples in negotiations (buyers understand them), keep DCF in your back pocket for sophisticated buyers or when the multiple needs defending. Nobody ever closed a main-street business sale on DCF alone — but plenty of sellers have used it to justify their multiple to a skeptical buyer’s CPA.
Common DCF Mistakes
Hockey-stick projections: flat near-term, explosive long-term. If the growth isn’t contracted or historically proven, it’s wishful thinking with decimal points. Too-low discount rates: using 10% (large-company rate) for a small business. Small businesses are riskier — 15–25% is honest.
Ignoring capex: projecting operating cash flow without subtracting the capital expenditures needed to sustain it. A business needing $100K annual equipment replacement has $100K less free cash flow than its P&L suggests. Perpetual growth above 3%: assuming the business outgrows the economy forever. It won’t.
False precision: presenting $1,847,293 as ‘the DCF value.’ With 60–80% of value in the terminal assumption, you’re kidding yourself with six significant figures. Present ranges: ‘$1.6M–$2.0M depending on discount rate.’ Honesty about uncertainty is a feature, not a bug.
A Simplified DCF You Can Do in 30 Minutes
Don’t need a full model? Here’s the quick version: (1) Take current normalized free cash flow (say $200K). (2) Assume 5% growth for 5 years. (3) Use 20% discount rate. (4) Terminal growth 2.5%. The math: PV of years 1–5 ≈ $680K, terminal value ≈ $1.4M discounted = $560K. Total ≈ $1.24M. That’s 6.2x current cash flow — sanity-check against industry multiples.
This 30-minute version captures 90% of a full DCF’s insight: whether the multiple-based price is economically reasonable. If the quick DCF says $1.2M and the seller wants $2M, you know the gap is 67% — and you know exactly which assumptions would need to be true to bridge it (impossible growth, tiny discount rate). That’s actionable intelligence from half an hour’s work.
The template: keep it simple, run multiple scenarios (optimistic/base/pessimistic), and use the range — not the point estimate — in decisions. DCF is a thinking tool that produces numbers, not a number-producing tool that replaces thinking.
Key Takeaways
DCF values future cash flows discounted for risk and time: project 5 years of free cash flow honestly, discount at 15–25% for small businesses, calculate terminal value with ≤3% perpetual growth, sum and cross-check against market multiples.
It’s most powerful as a validation tool and bullshit detector — not as a standalone pricing method. Run multiple scenarios, present ranges, and always reconcile with what the market actually pays.
A method valuing a business at the present value of its projected future cash flows: forecast 5 years, discount each year for risk/time (15–25% for small businesses), add a terminal value for beyond, and sum.
Terminal Value = Year 5 cash flow × (1 + perpetual growth) ÷ (discount rate − perpetual growth). Keep perpetual growth at 2–3%. Note: terminal value is often 60–80% of total DCF value.
15–25% for small businesses (risk-free rate + equity premium + small-company premium + company-specific risk). Higher risk = higher rate = lower value. Always test multiple rates — DCF is highly sensitive to this input.
Neither is ‘better’ — multiples reflect market reality (what buyers pay), DCF reflects economic logic (what cash flows justify). Use multiples for pricing, DCF for validation. When they disagree significantly, investigate before trusting either.