Asset-Based Business Valuation Method: How It Works in 2026
Of all valuation methods, the asset-based approach is the most concrete — and the most misunderstood. It values what the business OWNS, not what it EARNS. For some businesses, that’s the right lens. For others, it’s nearly irrelevant. Knowing which is which saves you from the most common valuation errors I see.
I’ve used asset-based valuation to price manufacturing acquisitions, settle partner buyouts, and establish floor values in negotiations. Here’s when it works, how to do it right, and where it breaks down.
What the Asset-Based Method Actually Values
The principle: a business is worth the fair market value of its assets minus its liabilities. Not book value (accounting fiction) — fair market value (what each asset would actually sell for). The gap between those two numbers is where the real work happens.
Two variants: going-concern asset value (assets valued as part of an operating business — machinery in place and running) and liquidation value (assets valued as if sold piecemeal tomorrow — always lower, typically 60–80% of going-concern value). Going-concern applies to healthy sales; liquidation to distressed situations, partner disputes, and downside analysis.
Why it matters even when you use other methods: asset value is the FLOOR. If your earnings-based valuation comes in below asset value, something’s wrong — either the business destroys value (possible in declining industries) or your earnings analysis missed something (more common). Every valuation should cross-check against the asset floor.
Tangible Assets: How to Value Them
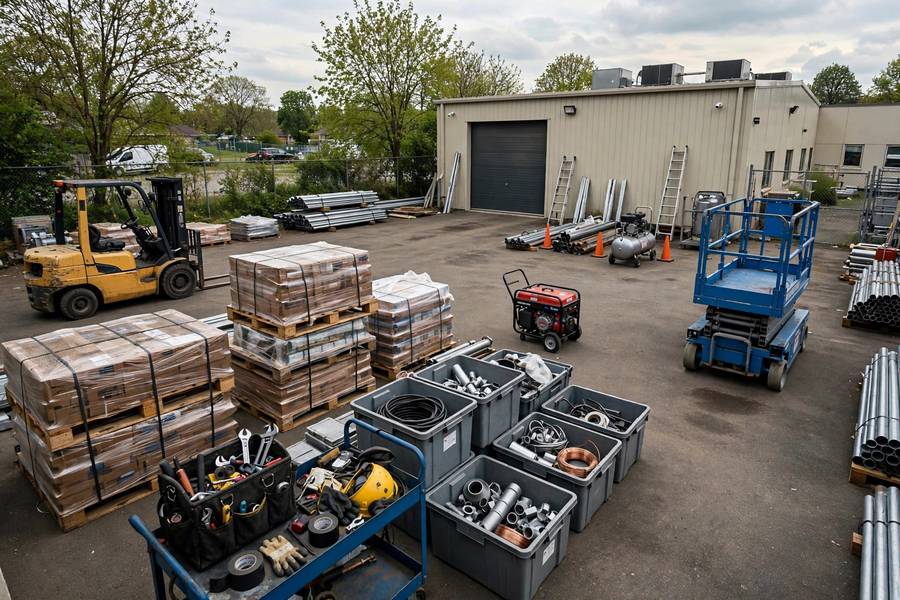
Real estate: get a commercial appraisal ($2K–$5K) — don’t guess, and don’t use tax assessments (they’re systematically off). If the business owns its premises, this is often the largest single asset. Equipment and machinery: fair market value in place, not depreciated book value. A 5-year-old CNC machine fully depreciated on the books might still be worth $80K — or $5K if obsolete. Get equipment appraisals for material items.
Inventory: value at the LOWER of cost or market, then discount for obsolescence. The classic trap: $200K of inventory on the books that’s really $60K of sellable goods plus $140K of dead stock. Physically inspect, check turnover rates, and write down aggressively — buyers certainly will. Receivables: face value minus realistic bad-debt reserves. A/R over 90 days is worth 50 cents on the dollar at best; over 180 days, near zero.
Cash and equivalents: face value — but distinguish operating cash (stays with the business) from excess cash (added to value). The purchase agreement should define normal working capital explicitly.
Intangible Assets: The Hard Part
Intangibles often exceed tangibles in value — and they’re harder to measure. Customer relationships and contracts: value based on expected future cash flows from existing relationships, discounted for attrition risk. Long-term contracts have clear value; informal repeat business has fuzzier (but real) value.
Brand and trademarks: valued via relief-from-royalty (what would you pay to license this brand?) or premium pricing analysis (how much more can you charge because of the brand?). For small businesses, brand value is usually modest — except in local markets where reputation IS the business.
Intellectual property: patents, proprietary processes, software, databases. Value via cost-to-recreate, market comparables, or income attribution. Most small-business IP is worth less than owners believe — ‘proprietary’ often means ‘undocumented’ to a buyer.
Workforce and systems: an assembled, trained team has value (cost to recruit and train replacements), as do documented systems. But these are the most fragile intangibles — they walk out the door daily. Value them conservatively, and only in going-concern scenarios.
The Adjusted Book Value Method
The most practical asset-based approach for small businesses: start with the balance sheet, then adjust every line from book value to fair market value. It’s systematic, auditable, and produces a defensible number.
The adjustment process: real estate (appraisal vs. book — often the biggest adjustment), equipment (FMV vs. depreciated book), inventory (write down obsolete), receivables (reserve for doubtful), intangibles (add — they’re usually absent from small-business balance sheets), liabilities (verify completeness — unrecorded liabilities are the killer).
Example: a distribution business shows $400K book value. Adjustments: real estate +$150K (appreciated), equipment +$40K (under-depreciated FMV), inventory -$60K (obsolete), receivables -$20K (doubtful), customer relationships +$100K (added intangible), unrecorded lease obligation -$30K. Adjusted asset value: $580K. That’s the floor — the earnings-based value should exceed it, or the business isn’t earning its cost of capital.
For the full valuation toolkit this method belongs to, my business valuation guide puts it alongside the income approaches.
When Asset-Based Valuation Is the RIGHT Method
Asset-heavy businesses: manufacturing, transportation, construction, agriculture — where equipment and real estate dominate value and earnings are cyclical. For these, asset value often approximates market value closely. Holding companies and investment entities: where the business IS its assets — no operating premium to calculate.
Distressed and liquidation scenarios: when earnings are negative or unreliable, assets are all you can value with confidence. Partner buyouts and divorces: where a conservative, defensible floor value prevents disputes — courts love asset-based valuations because they’re concrete.
Capital-intensive startups: pre-revenue companies with significant invested assets but no earnings history. The asset method values what’s actually there, not what might someday be.
When It’s the WRONG Method
Profitable service businesses: a consulting firm with $500K in earnings and $50K in assets is worth $1.5M on earnings — asset value says $50K. Using asset-based valuation here isn’t conservative; it’s wrong. The value is in relationships, reputation, and recurring revenue — none of which appear on the asset ledger.
High-growth companies: where current assets understate future earning power dramatically. Asset value is backward-looking; growth value is forward-looking. Businesses with significant unrecorded intangibles: brand, proprietary data, network effects — if these drive value, the asset method structurally understates.
The rule: asset-based valuation works when assets DRIVE earnings (manufacturing, real estate). It fails when earnings drive value independent of assets (services, software, brands). Match the method to the value source — this single judgment call determines whether your valuation is credible.
Liquidation Value: The Downside Case
Every buyer should know the liquidation value — it’s the worst-case recovery if the business fails. Calculate it as: orderly sale value of each asset (not fire-sale — 90–120 day marketing period), minus selling costs (commissions, legal, taxes), minus liabilities, minus wind-down costs (severance, lease terminations, contract penalties). selling a business
Typical recovery rates: real estate 85–95% of FMV, equipment 60–80%, inventory 40–60%, receivables 70–85%, intangibles 0–30% (customer lists and brand have minimal liquidation value). The blended result is usually 50–70% of going-concern asset value.
Why it matters: lenders use liquidation value for collateral assessment (it determines borrowing capacity), buyers use it as their walk-away floor (they’ll never pay less than they could recover), and sellers should know it for negotiation realism. A business worth $1M on earnings with $300K liquidation value gives the buyer $700K of intangible premium — which had better be justified by real earning power.
And when the downside case informs your entity planning, my LLC formation guide covers structuring that protects personal assets.
Combining Asset and Income Approaches
Professional valuations rarely use one method — they triangulate. The standard: calculate asset-based value (floor), SDE/EBITDA multiple value (market), and DCF (intrinsic) — then reconcile. When all three cluster, confidence is high. When they diverge, the divergence itself is informative.
Common reconciliation: asset value $580K, multiple value $900K, DCF $850K. Conclusion: the business is worth ~$850–900K, with $580K in hard asset backing (65% downside protection). That’s a well-supported valuation a buyer can underwrite — and a seller can defend.
Weight the methods by relevance: for asset-heavy businesses, weight asset value more; for service businesses, weight income approaches more. There’s no formula for the weighting — it’s professional judgment. But the discipline of calculating all three prevents the single-method blindness that causes the worst valuation errors.
Key Takeaways
The asset-based method values fair market value of assets minus liabilities — it’s the valuation FLOOR, not the ceiling. Adjust every balance sheet line from book to market value, add unrecorded intangibles conservatively, and verify liability completeness.
It’s the right method for asset-heavy businesses, distressed situations, and dispute resolutions — and the wrong method for profitable service businesses where earnings drive value. Always cross-check income-based valuations against the asset floor.
Valuing a business at the fair market value of its assets minus liabilities. It establishes the floor value — what the business is worth based on what it owns, independent of earnings.
For asset-heavy businesses (manufacturing, transportation), distressed sales, partner buyouts, divorces, and as a floor-value cross-check on every income-based valuation.
Customer relationships via discounted future cash flows, brand via relief-from-royalty, IP via cost-to-recreate or market comps. Value conservatively — most small-business intangibles are worth less than owners believe.
Going-concern values assets as part of an operating business; liquidation values them as piecemeal sale (typically 50–70% of going-concern). Lenders and downside analysis use liquidation; healthy sales use going-concern.