What Is a Partnership Business? The Honest Breakdown
Picture this: you’ve got the idea, your friend has the money, and neither of you has the time to do it alone. So you shake hands and start a business together. That raises the obvious question: what is a partnership business, exactly? It’s simply an arrangement where two or more people own and run a company together, splitting the profits, the losses, and the decision-making.
No corporation paperwork, no stock certificates, no board meetings. At its core, a partnership is the oldest business structure in the book — people pooling their resources and talents long before anyone invented the word “startup.” What makes it worth understanding today is how much depends on the details: what each partner puts in, who decides what, and what happens when things change.
What Is a Partnership Business in Legal Terms
In legal terms, a partnership is a business owned by two or more people who agree to share profits and losses. Each partner contributes something — money, property, skills, or labor — and in return gets a share of whatever the business earns or loses.
Here’s the part people miss: in most places, a general partnership forms the moment two people start doing business together for profit, whether or not anything is written down. That handshake deal with your friend? Legally, that may already be a partnership, with all the responsibilities that come with it.
The law also treats partners as agents of the business. That means one partner can sign a contract or make a commitment that binds the whole partnership — and all the partners — even if the others never agreed to it. It’s a feature that makes partnerships fast and flexible, and a risk that makes written agreements essential.
The Types of Partnerships
Not all partnerships work the same way. There are three main types, and the differences matter a lot:
General partnership. The default and simplest form. All partners share equally in management and profits (unless they’ve agreed otherwise), and — critically — all partners are personally liable for the business’s debts. If the business fails, creditors can come after each partner’s personal assets.
Limited partnership. This has two kinds of partners. General partners manage the business and carry full personal liability. Limited partners contribute money but don’t manage day-to-day operations, and their liability is limited to what they invested. This structure shows up in real estate ventures and investment funds.
Limited liability partnership (LLP). Common among professionals like lawyers, accountants, and consultants. Partners share management and profits like a general partnership, but each partner is generally shielded from the malpractice or negligence of the other partners — and, depending on the state, from the partnership’s debts.
How a Partnership Business Makes Decisions
Decision-making in a partnership runs on whatever the partners agree to — which is exactly why the agreement matters so much. By default, in a general partnership, each partner has an equal vote, regardless of who contributed more money. Without a written agreement, your partner who put in twenty percent of the capital has the same say as you.
Smart partnerships write down a different arrangement: voting rights tied to ownership percentages, certain decisions requiring unanimous consent (taking on big debt, adding a new partner, selling the business), and day-to-day authority delegated to whichever partner handles each area. A partnership agreement also covers how new partners join, how partners exit, and what happens to their ownership share — the questions nobody wants to discuss at the start and everyone wishes they’d resolved later.
There’s a useful companion topic here: how partnerships stack up against other small business structures. Our look at partnership pros and cons for small business goes deeper into the trade-offs.
How Profits and Losses Get Split
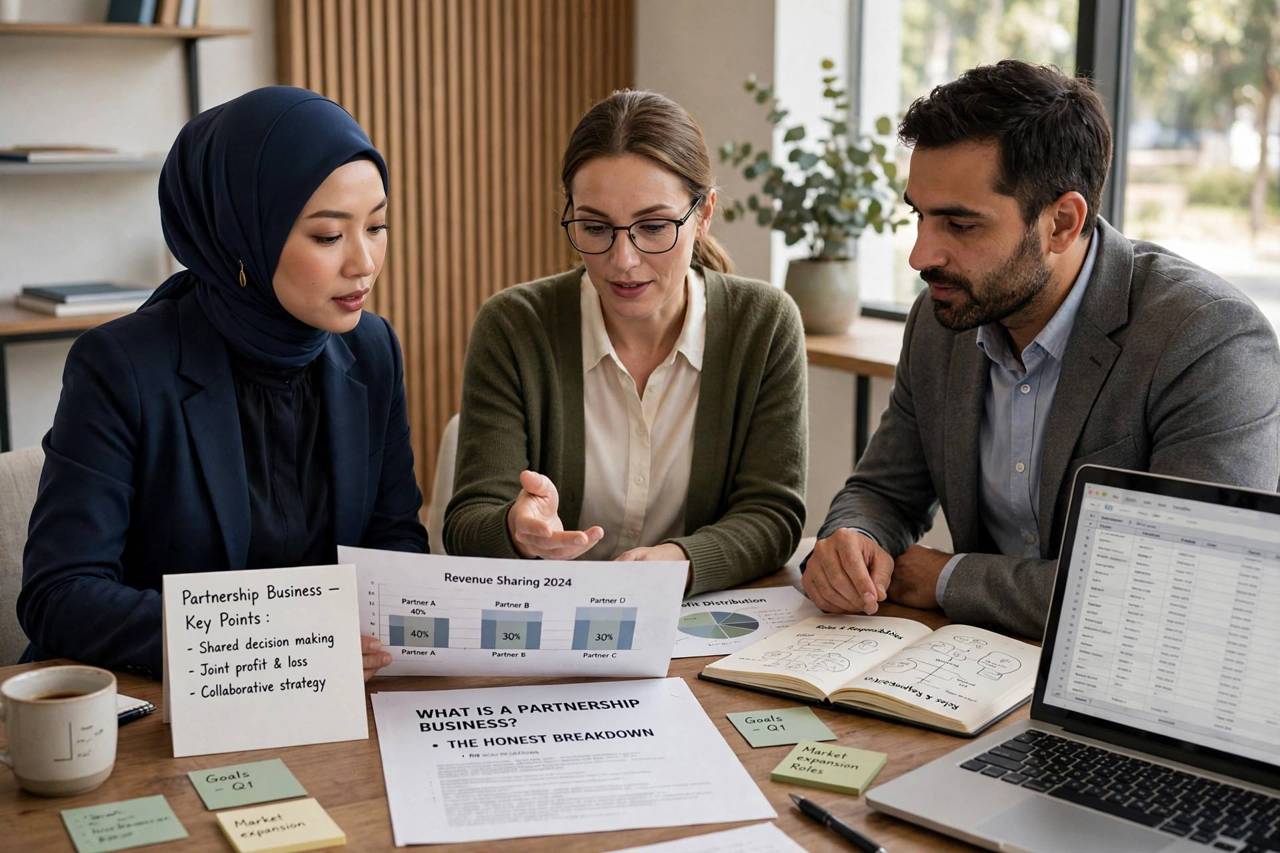
Profits in a partnership are divided however the partners agree — equally, by ownership percentage, by who brought in the clients, or by some formula that accounts for both capital and sweat. Without an agreement, the default is equal shares, which can feel unfair fast if contributions were wildly uneven.
Losses follow the same agreement. In a general partnership, each partner is personally on the hook for the business’s debts — not just their share, but the full amount. Creditors can pursue any partner for the entire debt and leave the partners to sort out reimbursement among themselves. This joint liability is the single biggest risk of the general partnership form.
For tax purposes, partnerships are pass-through entities: the business itself doesn’t pay income tax. Instead, profits and losses flow through to the partners, who report them on their personal returns. Each partner gets a Schedule K-1 showing their share. This avoids double taxation, but it means partners can owe tax on profits they never actually received in cash — a surprise that catches first-timers off guard.
The Real Advantages of Partnering Up
The appeal of a partnership is straightforward: more resources, more skills, more hands. Two people bring complementary strengths — one handles the product, the other handles the customers. The business can take on more work, weather slow months better, and benefit from a built-in sounding board for decisions.
Partnerships are also cheap and fast to start. There’s no state filing required for a general partnership in most places, no formation fees, no annual reports. You can begin operating almost immediately, which makes partnerships attractive for service businesses, creative projects, and ventures that need to move quickly.
And there’s a less obvious benefit: accountability. A good partner keeps you honest — about effort, about money, about whether the business is actually working. Solo founders have to manufacture that discipline themselves.
The Risks Nobody Warns You About
The risks of a partnership are the mirror image of its advantages. Joint liability means your partner’s business decisions can put your personal assets at risk — even decisions you didn’t know about. Disagreements over money, direction, or effort level are the most common reason partnerships fail, and without a written agreement there’s no agreed process for resolving them.
There’s also the exit problem. What happens when one partner wants out, gets divorced, dies, or simply stops contributing? In a general partnership without an agreement, one partner leaving can legally dissolve the whole business. A buy-sell clause — which sets how a departing partner’s share gets valued and paid for — is the single most undervalued page in any partnership agreement.
Finally, partnerships can make financing harder. Lenders often prefer the structure of an LLC or corporation, and bringing in outside investors is awkward when ownership is personal and informal. If growth and outside capital are in the plan, the partnership may be a starting point rather than a destination. For a broader look at getting a business off the ground, see how to start a business.
Partnership vs. LLC vs. Sole Proprietorship
Against a sole proprietorship, a partnership adds people — and with them, more capital and skills, but also shared control and the risk of liability for someone else’s actions. A sole proprietor answers to no one; a partner answers to their partners.
Against an LLC, the partnership’s main weakness shows: personal liability. An LLC with multiple owners (a multi-member LLC) gives partners the same flexibility to split profits and make decisions, while shielding each owner’s personal assets. Many partnerships eventually convert to LLCs for exactly this reason. The comparison at LLC vs. sole proprietorship touches on how liability protection changes the calculus.
Against a corporation, a partnership is simpler and cheaper with no double taxation — but a corporation scales better when you need investors, employees, and formal governance. Partnerships suit small, trust-based operations; corporations suit ambitions that outgrow handshakes.
Writing a Partnership Agreement That Actually Works
If you take one thing from this article, make it this: write the agreement before you need it. A solid partnership agreement covers at least these points:
- Each partner’s contribution — cash, property, equipment, or labor — and what it’s worth.
- Ownership percentages and how profits and losses are divided.
- Who makes which decisions, and which decisions need unanimous approval.
- Each partner’s role and expected time commitment.
- How new partners can join and how current partners can leave.
- How a departing partner’s share gets valued and paid out (the buy-sell clause).
- What happens if a partner dies, becomes disabled, or gets divorced.
- How disputes get resolved — mediation, arbitration, or something else.
Yes, it’s an awkward conversation to have with a friend or family member. It’s far less awkward than the conversation you’ll have without one. If the partnership involves significant money or assets, having a lawyer review the agreement is money well spent — and understanding how business valuation works helps when it’s time to price someone’s share.
When a Partnership Is the Right Call
Partnerships shine when the partners genuinely complement each other — one has the technical skill, the other has the network; one has the capital, the other has the time. They work well for professional practices, small service firms, creative studios, and real estate ventures where trust runs deep and the business stays small enough for everyone to stay informed.
They’re a poor fit when one partner carries all the risk while the other makes the decisions, when the business needs outside investors, or when the partners haven’t had the hard conversations yet. A partnership without a written agreement isn’t a plan — it’s a hope. Write the plan.
Frequently Asked Questions
How many people does a partnership need?
Two or more. There’s no upper limit, though partnerships with many partners usually formalize into LLPs or convert to LLCs as complexity grows.
Do I need a written agreement to have a partnership?
Legally, no — a general partnership can form through conduct alone. Practically, yes. A written agreement is what protects you on profit splits, decision rights, and exits, and operating without one is asking for a dispute.
Can a partner be held liable for another partner’s mistakes?
In a general partnership, yes — each partner can be personally liable for debts and obligations created by any partner acting in the business’s name. This is the key risk that LLPs and multi-member LLCs are designed to reduce.
How are partnership taxes handled?
The partnership itself generally doesn’t pay income tax. Profits and losses pass through to the partners, who report them on personal returns. Each partner receives a Schedule K-1 detailing their share — and may owe tax even on profits left in the business.
How does a partner leave a partnership?
The partnership agreement should say: typically the departing partner’s share is valued (often by an agreed formula or outside valuation) and bought out by the remaining partners or the business. Without an agreement, a partner’s departure can trigger dissolution of the partnership.