How to Improve Your Credit Score: 11 Proven Strategies
Your credit score affects more than loan approvals. Landlords check it, insurers use it to price policies, and lenders use it to set your interest rates. A strong score can save you thousands; a weak one quietly costs you money.
The good news: a score is a snapshot of habits, not a fixed trait. If you are starting from zero, learn what a credit score is and how it is calculated first, then work through these 11 strategies.
How Scores Are Built (The 30-Second Version)
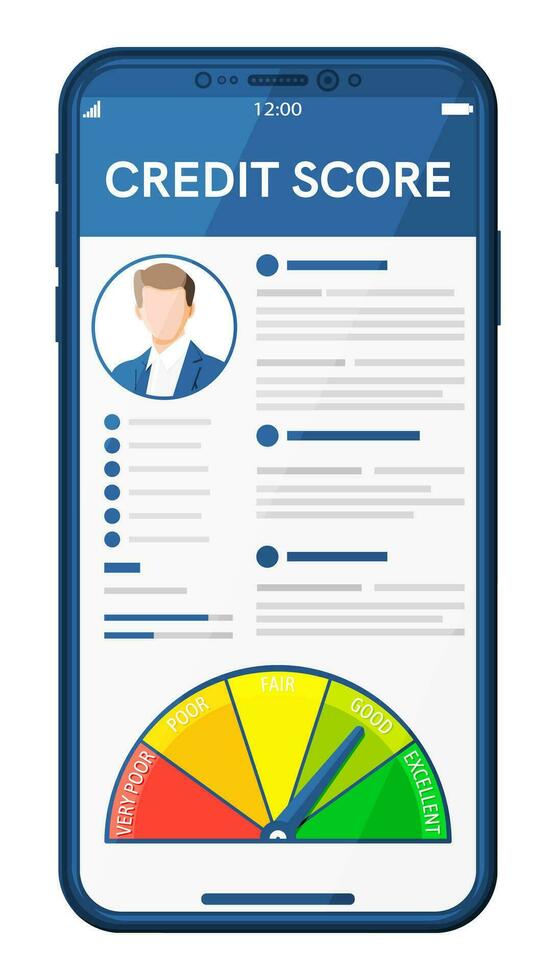
Most scores run from 300 to 850. Around 670 is good, 740+ is very good, and 800+ is exceptional. Two factors dominate: payment history (roughly 35% of a typical score) and how much of your available credit you use (about 30%). Length of history, new credit activity, and credit mix make up the rest. Understanding each piece of your credit score makes every strategy below easier to apply.
Before You Start: Know Your Baseline
Pull your free credit reports from Equifax, Experian, and TransUnion — they do not always match, so check all three. Read each one line by line for accounts you do not recognize, wrong balances, and late payments you are sure were on time. A meaningful share of reports contain errors, and a wrongly reported negative item is the easiest win on this list.
Note four numbers: your score, total credit limits, total balances, and the age of your oldest account. Everything below gets measured against these.
1. Pay Every Bill On Time
This is the single most powerful lever. One late payment can drag a good score down hard — the higher your score, the further it can fall. Lenders care most about one question: do you pay on time?
Pay at least the minimum on every account by its due date: cards, loans, utilities, medical bills. Past mistakes fade with time, and a fresh run of on-time payments gradually outweighs them. If money is tight in a given month, call the creditor before the due date — many offer short extensions that beat a late mark on your report.
2. Bring Your Credit Utilization Down
Utilization is the percentage of available credit you are using. $3,000 in balances on $10,000 of limits = 30%. Lower is better: keep it under 30%, and under 10% if you can.
This factor moves fast, so paying down card balances often shows results within a billing cycle or two. Two tactics: pay balances down aggressively, and pay more than once a month — issuers usually report your balance once per statement cycle, so a mid-cycle payment lowers the number the bureaus see.
3. Keep Old Accounts Open
The age of your oldest account and the average age of all accounts feed your score. Closing your first card — even one you rarely use — can shorten your history and hurt you.
If the old card has no annual fee, keep it open. Put one small recurring charge on it, like a streaming subscription, and set up autopay. It reports healthy payment history every month with zero effort. Only close a card if its annual fee outweighs the benefits — and even then, ask about downgrading to a no-fee version first.
4. Ask for a Credit Limit Increase
Raise your limits and your utilization drops without you paying down a cent. Many issuers accept increase requests online or by phone, and some grant automatic increases to customers with clean payment records.
Ask whether the request triggers a soft inquiry (harmless) or a hard inquiry (small, temporary dip) before you proceed. And one warning: a higher limit is a tool, not a permission slip. If extra room tempts you to spend more, skip this and focus on balances instead.
5. Become an Authorized User
If a trusted family member has a long-standing card with low balances and a perfect payment record, ask them to add you as an authorized user. That account’s history can appear on your report and lift your score — but only if the issuer reports authorized-user accounts, and only if the account is genuinely well managed. A maxed-out card will drag you down instead. You never need to use the card; the benefit comes from its history sitting on your file.
6. Dispute Every Error
Act on what you found in your baseline review. Dispute wrong balances, accounts that are not yours, and on-time payments reported as late, with each bureau that lists them. You can file online, by mail, or by phone, and the bureau generally has about 30 days to investigate.
Include evidence: payment confirmations, creditor correspondence, identity documents. One removed error — especially a serious one like a collection — can lift your score meaningfully. This is free score improvement, and most people skip it.
7. Set Up Autopay for Everything
A missed due date is the most avoidable way to damage a score. Set autopay for at least the minimum on every credit account, then pay extra manually when you can. Even in your most chaotic month, nothing is ever late. For bills without autopay, set calendar reminders a few days before the due date. A small system beats a good memory.
8. Space Out New Applications
Each credit application typically triggers a hard inquiry, which can shave a few points off your score. One is minor; several in a short window looks like desperation.
Do not apply for three store cards in one shopping trip. If you are rate-shopping for a mortgage or auto loan, multiple inquiries of the same type within about two weeks are generally treated as one, since scoring models expect comparison shopping. If you do not need new credit, do not apply — every avoided inquiry is a small favor to your score.
9. Let Your Credit Mix Build Naturally
Scoring models like seeing different account types handled responsibly — revolving accounts like cards plus installment accounts like auto or student loans. This is a small factor. Never take out a loan you do not need to check a box. But if you already carry installment debt, your on-time payments are quietly helping. Let this one build over time while the bigger strategies do the heavy lifting.
10. Deal With Collections Head-On
Accounts in collections weigh on your score until they age off, but ignoring them is the worst option. Paying or settling is generally better, and some newer scoring models ignore paid collections entirely.
For a single late payment on an otherwise spotless record, try a goodwill letter: a polite, specific request to the creditor to remove the mark. It works more often than people expect. And avoid any company that promises to erase accurate negative information for a fee — no one can legally do that.
11. Build a Small Emergency Buffer
Most missed payments are not about irresponsibility — they are about a car repair or a slow month colliding with a due date. Even $500 to $1,000 in a separate savings account can keep one bad month from becoming a late payment. Automate a small transfer each payday. This strategy does not raise your score directly; it protects everything the other ten build.
How Long Will This Take?
Lowering high utilization can move your score within one or two billing cycles. Fixing report errors can pay off in about a month. Rebuilding after missed payments or collections is measured in months, and deep damage can take a year or more of consistent behavior. There is no legitimate shortcut.
Three Mistakes That Quietly Hurt Scores
Closing old cards to “simplify.” This can shorten your history and raise utilization at once. Ignore the card instead of closing it.
Carrying a balance because you heard it helps. It does not. Paying in full builds the same positive history without a cent of interest.
Panicking at small dips. Scores wobble a few points month to month. Checking your own score never hurts you (it is a soft inquiry) — watch the trend over quarters, not the noise over days.
FAQs
If high utilization is the main problem, expect meaningful movement within 30 to 60 days of paying balances down. Disputing errors works on a similar timeline. Rebuilding after missed payments or collections usually takes several months to a year of consistent on-time behavior.
No. Checking your own score is a soft inquiry with zero effect. Only hard inquiries — made by lenders when you apply for credit — can affect your score, and their impact is small and temporary.
Around 670 is generally considered good; 740+ is very good and 800+ is exceptional. Aim for the score that qualifies you for the rates you want on the borrowing you actually plan to do.
Not automatically, though some newer scoring models ignore paid collections. You can request a “pay for delete” agreement in writing before paying, but the collector is not obligated to agree. A paid collection still looks better to manual reviewers than an unpaid one.
Usually no — especially no-fee cards with long history. Keeping them open preserves your history length and total available credit. The exception is an annual-fee card that is not earning its keep; ask about downgrading before closing.
Yes. Options include credit-builder loans from community banks or credit unions, becoming an authorized user on a well-managed card, and rent-reporting services. A secured card — where your deposit becomes your limit — is another common starting point.
The Bottom Line
Pick the two or three strategies that match your biggest weaknesses and work them for a quarter, then measure against your baseline. For a refresher on how credit scores are calculated and what each range means, keep that guide handy — it is the map, and these strategies are the route.
Pingback: What Is Compound Interest? Formula, Examples, and How It Works - Wedlockcross
Pingback: What Is a Credit Score? Ranges and Factors